Siding Financing Options: How to Pay for a Home Exterior Upgrade
When considering a home exterior upgrade like siding replacement, it’s essential to explore the various financing options available to fund the project. Here, we will discuss different ways you can finance your siding upgrade and the pros and cons of each method.
When it comes to financing home exterior improvements like siding, personal loans can be a viable option for homeowners looking to upgrade their property. Personal loans are unsecured loans that can be used for various purposes, including home renovation projects.
Personal loans for siding upgrades work by providing homeowners with a lump sum of money that can be used to cover the costs of materials, labor, and other expenses associated with the project. These loans typically have fixed interest rates and monthly payments over a set term.
Applying for a personal loan for siding upgrades usually involves filling out an online application with personal and financial information. Lenders will assess the applicant’s credit score, income, and debt-to-income ratio to determine eligibility. Good credit history and a stable income are generally required to qualify for a personal loan.
Interest rates for personal loans can vary depending on the borrower’s creditworthiness, the loan amount, and the lender. On average, interest rates for personal loans range from 6% to 36%. Borrowers with excellent credit scores may qualify for lower interest rates, while those with poor credit may face higher rates.
Some reputable financial institutions that offer personal loans for siding projects include banks like Wells Fargo, Chase, and Citibank, as well as online lenders such as SoFi and LightStream. It’s essential to compare loan terms, interest rates, and fees from different lenders to find the best option for your siding upgrade.
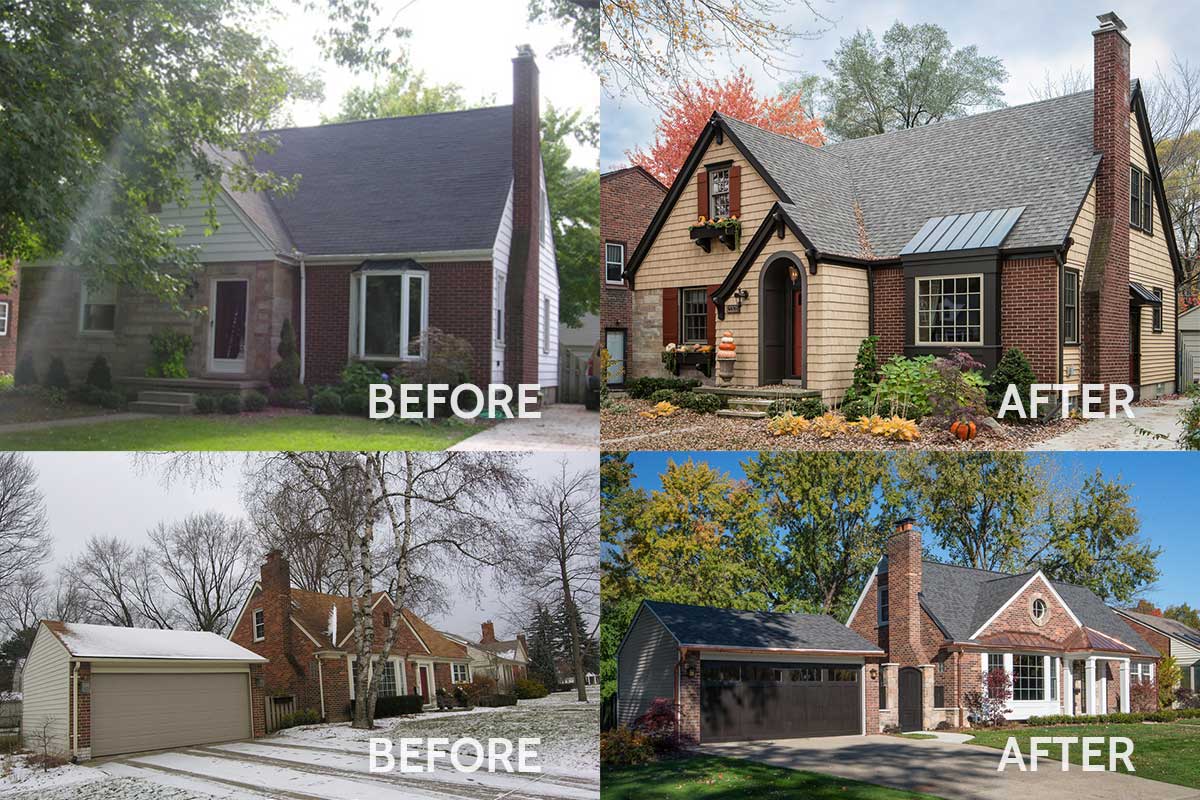
When it comes to financing home exterior projects like siding upgrades, homeowners have the option to leverage their home equity through loans or lines of credit. Home equity is the value of a homeowner’s interest in their home, calculated by the difference between the home’s market value and the outstanding balance on any mortgage or other debts secured by the property.
The interest rates on home equity loans are usually fixed, providing predictability in terms of monthly payments.
The interest rates on HELOCs are typically variable, meaning they can fluctuate over time.
Risks and Benefits of Using Home Equity for Siding Financing
Using home equity as a financing option for siding upgrades comes with both risks and benefits. Here are some key points to consider:
When considering siding installations, contractor financing can be a convenient option to help manage the costs. Here’s how it works:
What are some common financing options for siding upgrades?
Common financing options include personal loans, home equity loans, credit cards, and contractor financing. Each option has its own pros and cons to consider.
How do personal loans work for financing siding projects?
Personal loans provide a lump sum amount that can be used for siding upgrades. Borrowers repay the loan amount with interest over a fixed period of time.
What is the difference between home equity loans and lines of credit for financing siding projects?
Home equity loans provide a lump sum upfront, while lines of credit offer a revolving credit line that homeowners can draw from as needed for siding projects.